
Democratic Party Rep. Kim Young-jin Proposes Bill to Prevent Corporate Real Estate Gap Investment
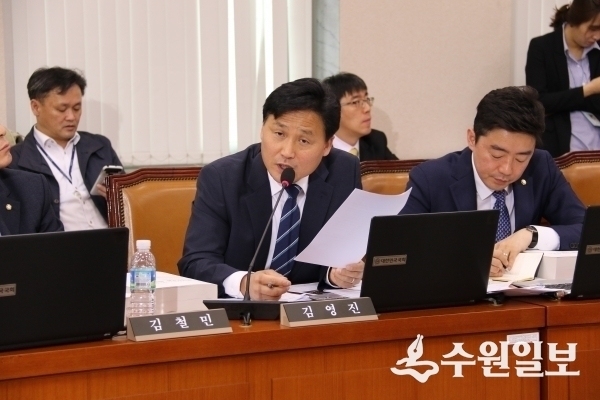
[Suwon Ilbo=Reporter Seo Dong-young] Rep. Kim Young-jin, Deputy Floor Leader of the Democratic Party, announced on the 21st that he has introduced an amendment to the Corporate Income Tax Law to prevent gap investment using non-business real estate by corporations.
According to Rep. Kim Young-jin, there has been a recent increase in cases where corporations are established and real estate is traded to evade real estate-related regulations that apply to individuals, such as celebrity building owners, and public opinion on the need for regulation has grown.
Under current law, when a corporation transfers housing, vacation homes, and non-business use land, an additional 10% corporate income tax is imposed on the transfer income of the relevant land and buildings. However, in the case of individuals, a maximum of 42% capital gains tax is imposed on housing and similar properties, and up to 50% is imposed when the holding period is less than one year.
According to the National Tax Service, the number of corporations that reported additional corporate income tax on transfer income from land, etc., over the past five years increased more than threefold from 1,175 in 2014 to 3,978 in 2018. Accordingly, the registered assets increased more than sixfold during the same period from approximately 500 billion won to approximately 3.1 trillion won. Corporations are generating profits by investing in non-business use land instead of productive economic activities, while paying significantly less tax compared to individuals.
Additionally, unlike individuals, there is no provision for corporations to impose additional tax on capital gains when they hold non-business real estate for a short period and then sell it. As a result, short-term small-scale investment is prevalent, particularly in non-regulated areas in provincial regions, disrupting the real estate market.
Accordingly, the amendment proposes to increase the corporate tax rate on capital gains to 30% when a corporation transfers housing, vacation homes, and non-business use land. Furthermore, when the relevant real estate is held for a short period and then transferred, a tax rate of 40% will be applied to prevent real estate speculation using corporations.
Rep. Kim Young-jin stated, “It is necessary to increase the corporate tax rate on gap investment that abuses the establishment of corporations for fair taxation,” and explained the purpose of the bill: “By increasing the surtax on capital gains from corporate housing and non-business use land transfers and imposing additional tax on transfers after short-term holding, we will prevent real estate speculation using corporations and contribute to stabilizing the real estate market.”