
Editorial Will President Lee Jae-myung Follow Moon Jae-in Season 2 or Return to Pragmatism?
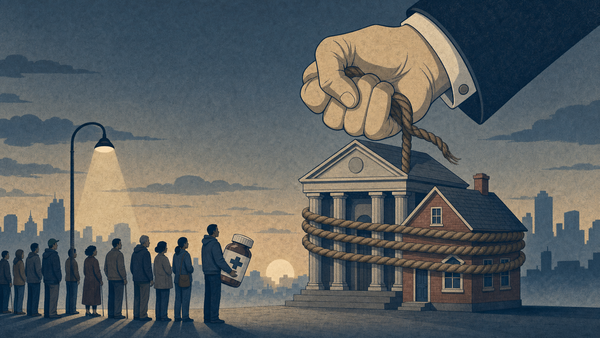
The two pillars of the government's real estate policy are both derailing. One is the tax reform plan, which involves adjusting the basic deduction for comprehensive property tax on non-resident single-homeowners and restructuring the long-term holding special deduction to be based primarily on occupancy period. The other is quantitative controls on household loans, a measure that sets a ceiling on the amount of annual loan increases per financial institution and tightens bank lending windows.
The Limitations of Loan Regulations Dependent on Administrative Guidance
Let us examine the quantitative controls. These regulations take the form of administrative guidance based on the financial authorities' macroprudential supervisory authority. However, because the law does not specify concrete guidelines, this has drawn criticism for amplifying market uncertainty. Financial institutions submit annual targets aligned with the authorities' "management direction," and if they exceed these targets, they face disadvantages in inspections and oversight the following year. The Constitution stipulates that restrictions on citizens' basic rights can only be imposed through law (Article 37, Section 2) and declares respect for individuals' and enterprises' economic freedom and creativity (Article 119). This is why criticism has emerged during parliamentary audits such as the National Assembly's Legislative and Judiciary Committee, stating that regulations directly affecting citizens' exercise of property rights operate through window guidance without clear legal standards, with uncertainty reaching nearly the level of abuse of authority.
Major developed countries manage household debt primarily using legalized standards such as DSR and LTV, which assess borrowers' repayment capacity and ensure predictability. In contrast, uniformly constraining the total loan amount per financial institution easily induces supply-demand distortions. Similar to the quantitative loan controls Japan introduced during its bubble collapse in 1990, overly artificial restraint measures can deliver unexpected shocks to the market, necessitating cautious approaches.
Every time the government strengthens quantitative management by setting loan growth rate targets, market side effects have recurred. As regulations are tightened and a lending cliff for actual homebuyers emerges, exceptions are created and then relaxed again, turning real estate finance into a patchwork. This is why complaints continue from actual homebuyers waiting in line from dawn to receive loan applications or unable to secure down payments for their purchased apartments. With cycles of tightening, adding exceptions when side effects emerge, and then loosening again, even the Bank of Korea's Monetary Policy Committee has expressed concern that quantitative controls are undermining the effect of base rate adjustments.
Tracing the ancestry of this drastic measure is even more disheartening. The Moon Jae-in government in 2021 formally implemented quantitative management by setting specific growth rate targets. That year's growth rate was 5-6%, but it exceeded the target at 7.1%. When banks halted new lending at year-end, creating a lending cliff for actual homebuyers, the government hastily exempted jeonse (long-term lease) loans.
The Lee Jae-myung government revived that failed measure and applied it more harshly. Beginning with the June 27 measures last year that uniformly capped mortgage loan limits at 600 million won, it proceeded through the September 7 and October 15 measures, differentiating limits at 600 million, 400 million, and 200 million won depending on property values. In April this year, under the banner of "severing the link between real estate and finance," it tightened household loan growth rates to 1.5%. Then, just four months later, it raised the white flag. "Loan open runs"—where applications close within 10 minutes of opening at 6 a.m.—became everyday occurrences. As actual homebuyers unable to secure down payments for their purchased apartments voiced their pleas at a presidential forum, on the 13th the government announced measures doubling the quantitative target to 3%. With cycles of tightening, adding exceptions when side effects emerge, and then loosening again, real estate finance has become a patchwork. Even the Bank of Korea's Monetary Policy Committee expressed concern that quantitative controls are undermining the effect of base rate cuts. How can citizens be asked to make life plans when the government cannot forecast even four months ahead?
Damage to Actual Homebuyers from Inelegant Tax Design
The tax system too lacks sophisticated design. Despite the government's intent to strengthen taxation on non-resident single-homeowners from a tax justice perspective, the current tax system risks imposing excessive burdens on well-meaning actual homebuyers. Prime examples include office workers temporarily away from home due to job transfers or work circumstances, and those who became non-resident single-homeowners through inherited shares.
Certainly, the tax law includes exceptional provisions for unavoidable reasons such as work-related circumstances or medical care. However, the verification procedures are cumbersome and requirements strict, creating blind spots. Additionally, single-homeowners who temporarily fail to meet residency requirements during home transfers face excessive capital gains tax burdens. Capital gains from residential moves do not represent income accumulating in bank accounts but rather funds for residential relocation needed to enter the next home. In a situation of overall rising home prices, excessive capital gains tax can constrain upward residential mobility.
Major countries such as the United States and the United Kingdom grant generous deduction limits for residential homes or operate flexible exemption systems proportional to occupancy periods to ensure single-homeowners' residential moves. Taxation on actual homebuyers with one home should be finely calibrated to the line of preventing market speculation. It is necessary to improve the mechanical design that punishes based solely on holding and occupancy periods and to adopt a straightforward approach that opens the path for actual homebuyers' residential transitions.
Must Return to Market Communication and Predictable Policy
We have seen this scene before. Under the banner of "war on speculation," the Moon Jae-in government rolled out more than twenty measures over five years. Heightened capital gains taxes on multi-homeowners increased gifts instead of supply, and demand avoiding tax burdens converged on "one solid house," pushing up Gangnam real estate prices. The Jeonse Protection Act (Lease Two Laws) returned with the disappearance of jeonse listings and skyrocketing jeonse prices. Despite witnessing for five years how policies designed with noble intentions and logic invite retaliation in the market, the current government is walking the same path, reviving quantitative controls and further tightening tax policy. It is strange that the term "Moon Jae-in Season 2" is not being used.
No matter how noble the intention, policies that ignore market principles produce unintended side effects. We must not repeat the past experience in which multi-homeowner regulations resulted in inventory lockup and "one solid house" concentration. We have already witnessed multiple times what chaos policies designed with only noble intentions and enthusiasm bring to markets.
Pushing ahead with foreseeable side effects is not conviction but stubbornness. The government must boldly change what can be changed by accepting voices from the field. Short-term measures originating from the president's ideas must cease, replaced by stable, predictable policies verified in advanced nations. The government should present a roadmap for converting quantitative controls to borrower-unit regulations based on law and boldly reduce the tax burden on single-homeowner actual homebuyers as the starting point. Under a policy structure of perpetual extreme measures, normal market operations cannot be expected.
Whether tomorrow's (18th) press conference becomes the prelude to Moon Jae-in Season 2 or the beginning of pragmatist Lee Jae-myung's government depends on President Lee Jae-myung.