
KOSDAQ Listing HaechiTech ② Put-Back Options Ticking...DB Securities "Will Actively Respond When Repurchase Inflows Occur"
DB Securities, which led HaechiTech's listing, has taken on a dual burden. Following the acquisition of unsold shares at its own expense due to institutional subscription shortfalls in the primary offering, the burden of put-back options (repurchase rights) from retail subscribers has materialized as the stock price has fallen more than 30% below the offering price.
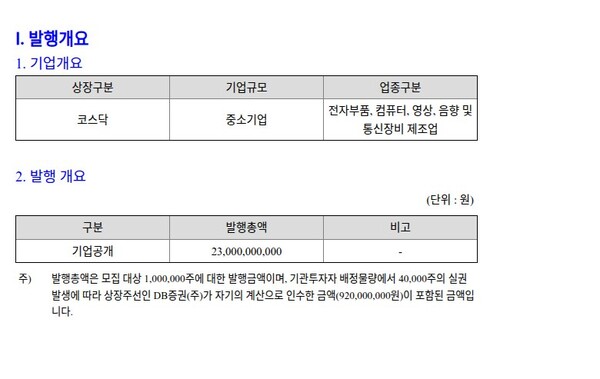
According to the securities issuance performance report submitted to the Financial Supervisory Service's electronic disclosure system on the 28th, for the HaechiTech IPO, institutional investor allocations totaled 750,000 shares, but subscriptions only reached 710,000 shares. Due to this exceptional shortfall where institutional demand fell short of allocated volume, 40,000 unsold shares (worth 920 million won) were acquired at DB Securities' own expense as the lead underwriter. The retail subscription competition ratio also remained at just 25.7 to 1. Of the institutional investor allocation, 94.4% was non-committed mandatory holding volume.
The unsold shares acquired at the 23,000 won offering price are already in the range of approximately 300 million won in unrealized losses based on the 28th closing price of 15,120 won.
The greater burden comes from the repurchase rights. HaechiTech, as a company listed via technology exception provision, obligated DB Securities as the underwriter to grant repurchase rights to 250,000 shares allocated to retail subscribers at 20,700 won per share (90% of the offering price) over a six-month period from the listing date. With the current stock price falling approximately 27% below the exercise price, retail subscribers holding the shares without selling have strong incentive to exercise the repurchase rights.
If all 250,000 shares allocated to retail subscribers are returned for repurchase, the amount DB Securities must purchase reaches 5.175 billion won. Considering the difference from the 28th closing price of 15,120 won, a loss burden of approximately 1.4 billion won could be created. However, if subscribers have sold the shares or withdrawn them from their allocated accounts, the rights expire, and if the KOSDAQ index falls more than 10% compared to the listing date, the exercise price is adjusted, so the actual burden scale remains fluid.
DB Securities must also mandatorily hold 78,673 shares acquired within six months before applying for the listing preliminary review for six months after listing, and 30,000 shares (3% of IPO shares) at the same price as the offering price for three months. Adding the unsold share acquisition portion, the underwriter holds directly 149,000 shares of the issuer.
◇ Disclosure States 'Unsold Shares Occurrence from Institutional Allocation'...DB Securities Official: "Not Acquisition Due to Shortfall"
The market is again questioning the appropriateness of offering price determination. HaechiTech entered via technology exception after receiving an A grade from both the Korea Technology Finance Corporation and NICE Investors Service for its core technology (high-precision 3D magnetic sensor SoC), but it is an unprofitable company recording net losses consecutively in 2024 and 2025. The demand forecast competition ratio was recorded at 101.9 to 1, but the volume with committed mandatory holding commitments was only 5.6% of the allocation basis, and the offering price was set at 23,000 won, the lower end of the target band (23,000 to 28,000 won). Nevertheless, institutional demand fell short of allocated volume in the primary offering, meaning even the lower end of the band was not accepted by the market. The stock price on the first listing day plummeted 39.4% below the offering price.
Regarding this, a DB Securities official stated to Suwon Ilbo, "It's not an acquisition due to shortfall but rather shares originally obligated to be purchased." However, the securities issuance performance report submitted to the Financial Supervisory Service states "Due to the occurrence of 40,000 unsold shares from the institutional investor allocation, the listing promoter acquired them at its own expense." When asked whether there was any evidence of pre-committed mandatory purchase, the official responded, "I cannot confirm that." A securities industry expert noted that if DB Securities' explanation that this was a mandatory purchase volume is correct, it raises questions about why the disclosure stated "occurrence of unsold shares from institutional investor allocation."
Regarding the repurchase rights, the official stated, "Repurchase requests have not yet come in" and "We plan to actively prepare response measures as they come in." Regarding the weak stock price, the official said, "The IPO market overall is not favorable, so it's not the atmosphere of rapid surges immediately after listing like in the past" and "Since not just HaechiTech but other IPOs are underperforming, couldn't there be an influence from market sentiment?"
NearLabs, which listed around the same time, is also trading below its offering price, with Samsung Securities as the underwriter's repurchase right burden being discussed, indicating that the underperformance of second-half KOSDAQ IPOs is spreading as an underwriter risk.